How much is insurance on a Kia K5?
A 2024 Kia K5 runs about $2,270 a year for a typical 45-year-old, $330 more than an average car of the same age, because of more injury claims, higher crash-repair losses, more damage to others' property, and higher non-crash losses. Putting a new 16-year-old on a family policy with the K5 adds about $1,500 a year (#8 of 9 midsize four-door cars we compare).
2024 Kia K5 (K5), national average
about $2,270 a year (about $190 a month)
Estimated range: $1,650–$3,300. Actual quotes can fall outside it.
An average car of the same age (what HLDI's 2022–24 results measure against) runs about $1,940 a year. A used 2022 K5 drops to about $2,150 (see the table below).
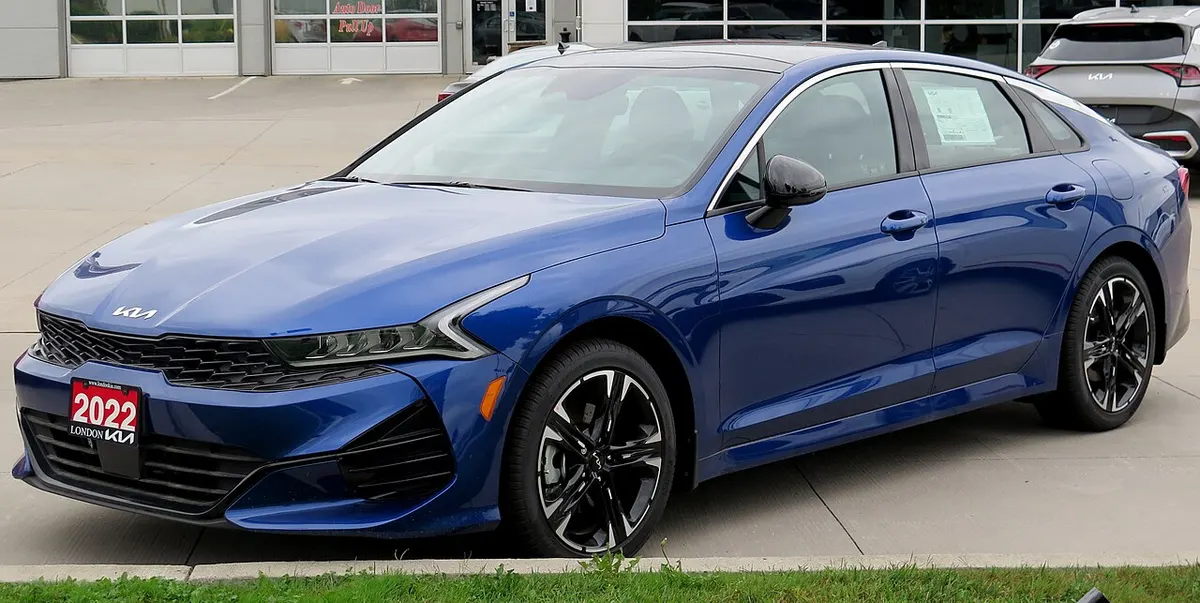

Priced for the 2024 K5, the newest year covered by HLDI's loss data (2022–24 models), for a 45-year-old driver with a clean record and full coverage. HLDI's results combine drivers of all ages. We apply them to one example driver (a 45-year-old with a clean record) so pages are comparable; they aren't specific to 45-year-olds. Each state raises or lowers every car's price by the same percentage, so the Kia K5's rank is the same in every state.
Why the Kia K5 costs what it does
What HLDI reports (2022–24 models, all drivers combined)
The Highway Loss Data Institute (HLDI) compares each model's insurance losses with an average car's. For the Kia K5 2WD/4WD, on HLDI's scale where 100 is an average car and lower is better, it reports 144 for crash repairs, 116 for non-crash damage, 125 for damage to others' property, and 155 for injury claims.
- Crash repairs (collision)fixing this car after a crashWorse than average44% worse than averageworst of the 9 midsize four-door cars we compare
- Non-crash damage (comprehensive)theft, weather, fire, vandalism, glass, and animal strikesAverage16% worse than average8th best of the 9 midsize four-door cars we compare
- Damage to others' property (property damage liability)other people's cars and property, when this car's driver is at faultWorse than average25% worse than average7th best of the 9 midsize four-door cars we compare
- Injuries to others (bodily injury liability)how often injury claims are filed against this car's drivers, not how much they costSubstantially worse than averagefiled 55% more often than average6th best of the 8 midsize four-door cars we compare
HLDI rates results within about 20% of average as “Average.”
Source: HLDI, insurance losses by make and model, 2022–24 models.
What we estimate that means for price
Prices move less than loss results do: a car's loss record is only one of many things insurers weigh, and each weighs it differently. So we count only part of HLDI's difference. Combining crash repairs and non-crash damage (weighted about 71% and 29%, the share each makes up of industry claim costs), the Kia K5 comes out about 36% worse than average. We count about a third of that difference, so the part of the bill that fixes the car is about 12% more than average: about $1,070 a year vs $950. On the liability side, damage to others and injury claims combine to about 42% worse than average. We count about half, so that part is about 22% more: $1,210 a year vs $990.
In EPA size classes, the K5 is a large car (gas-powered). In Highway Loss Data Institute loss tables, the Kia K5 is benchmarked against midsize four-door cars.
- This car's repair losses run a bit above the cars we could check against real prices, so the range reaches higher.
Matched to HLDI series “Kia K5 2WD/4WD” (HLDI, 2022–24 models).
A used Kia K5, by model year
| Model year | Full coverage | Liability only | Adding a teen | Teen on their own policy |
|---|---|---|---|---|
| 2024 K5 (0–3 years old) | about $2,270 | about $1,210 | +$1,500 | about $6,530 |
| 2022 K5 (4–7 years old) | about $2,150 | about $1,210 | +$1,420 | about $6,160 |
Our catalog covers the Kia K5 across model years 2021–2027. Full coverage on a used 2022 K5 (4–7 years old) runs about $2,150 a year, $130 less than on a 2024. Dropping collision and comprehensive on that 2022 brings liability-only coverage to about $1,210 a year. Each photo shows that year's generation of the car. Photo credits.
All 2 versions of the 2024 Kia K5 in our catalog (K5 and K5 AWD) price within about $50 a year of each other.
On a policy of their own with a 2024 Kia K5, a 22–25-year-old pays about $2,960 a year ($680 more than a 45-year-old), a 26–39-year-old about $2,520, and a driver 65 and older about $2,390.
Adding a 16-year-old with a Kia K5
A new driver costs more with any car, and more than usual with the Kia K5: adding a 16-year-old raises the family bill by about $1,500 a year ($125 a month), $220 more than adding a teen with an average car of the same age. A separate policy in the 16-year-old's own name runs about $6,530 a year ($5,030 more than adding them to the family policy).
For adding a teen driver, the Kia K5 ranks 15th most expensive out of all 121 models we track. Stepping down to a used 2022 K5 (4–7 years old) brings the teen add-on to about $1,420 a year.
That increase is how much the family bill goes up with a new 16-year-old driving this car. Cheapest cars to insure for a teen.
Similar midsize four-door cars
Among these 9 midsize four-door cars, the Kia K5 is the 2nd most expensive to insure. Right next to it are the Chevrolet Malibu (about $2,250 a year) and the Nissan Altima (about $2,290).
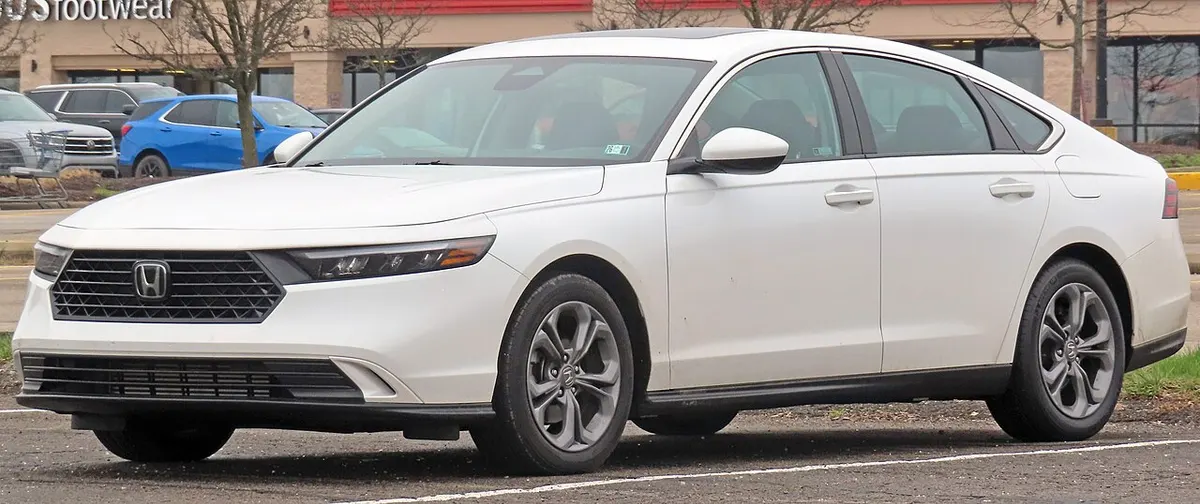 2024 Honda Accordabout $2,070 ($210 less)
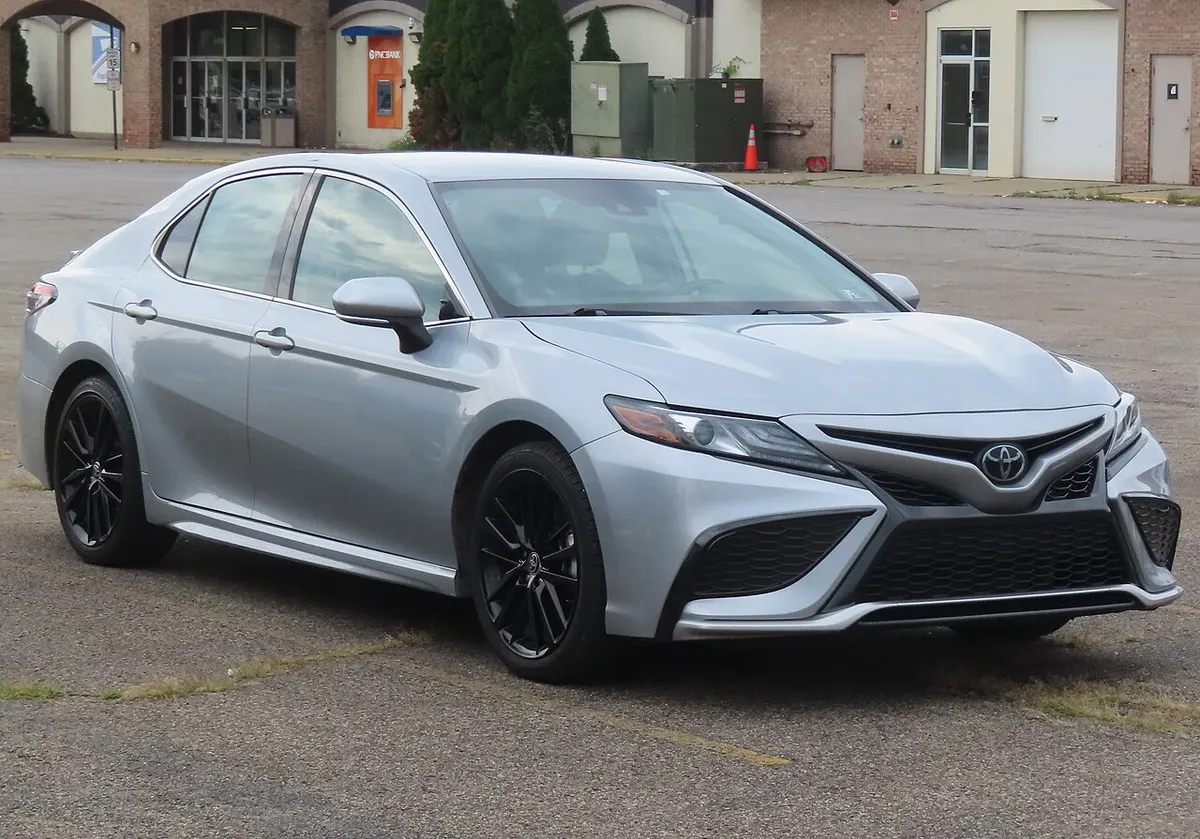 2024 Toyota Camryabout $2,090 ($190 less)
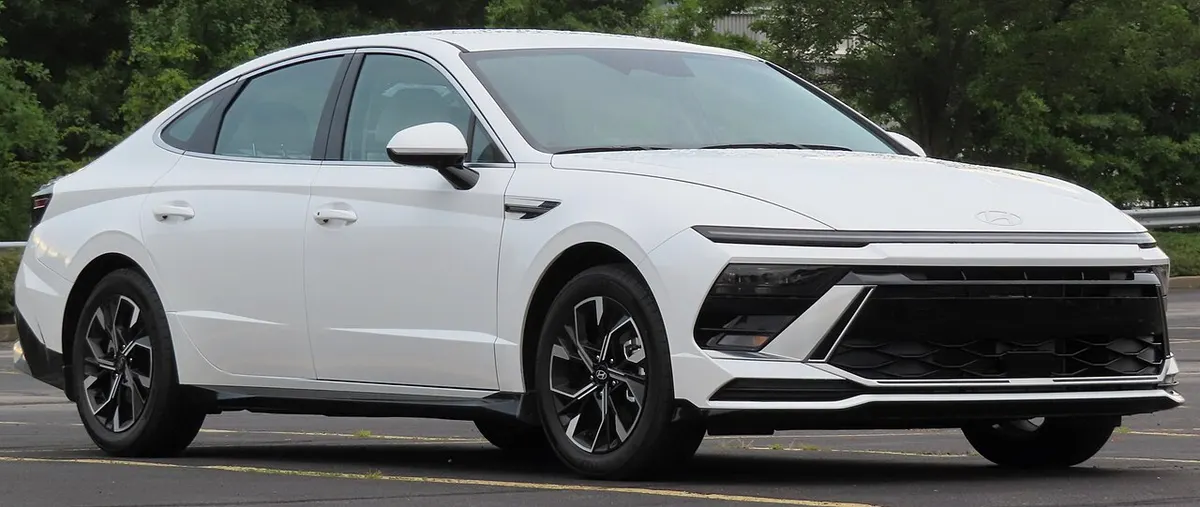 2024 Hyundai Sonataabout $2,160 ($110 less)
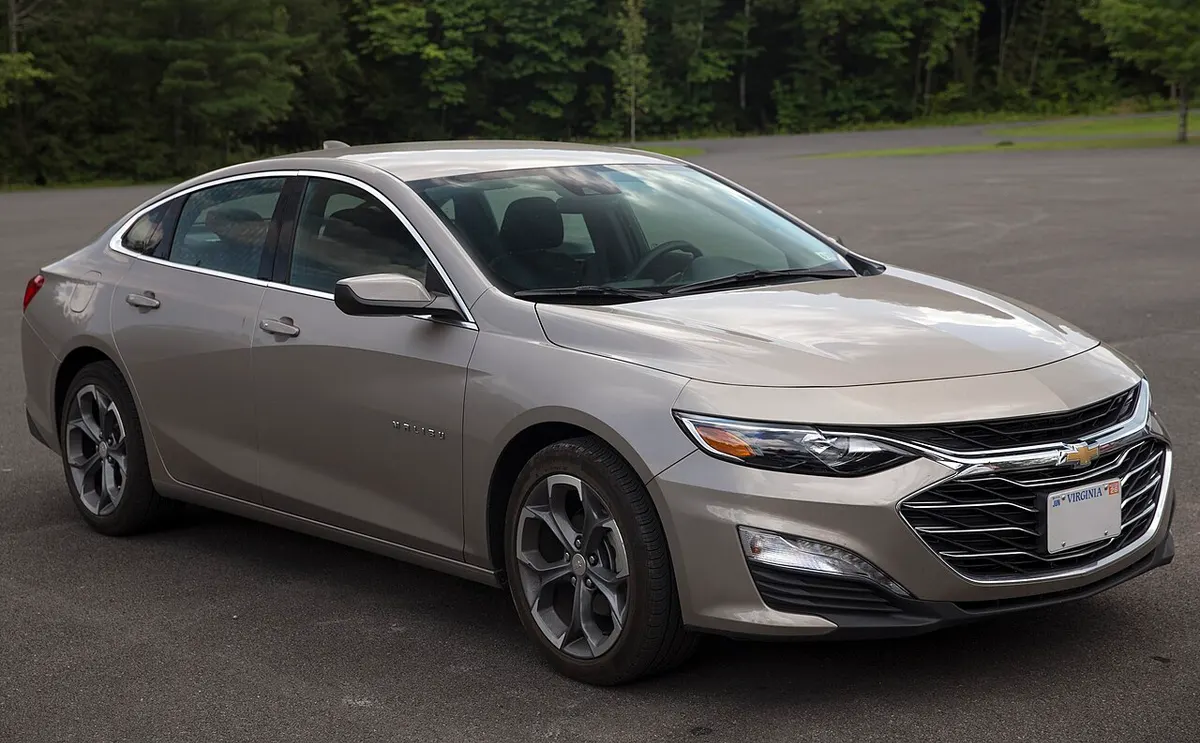 2024 Chevrolet Malibuabout $2,250 (about the same)
- 2024 Kia K5about $2,270 (this car)
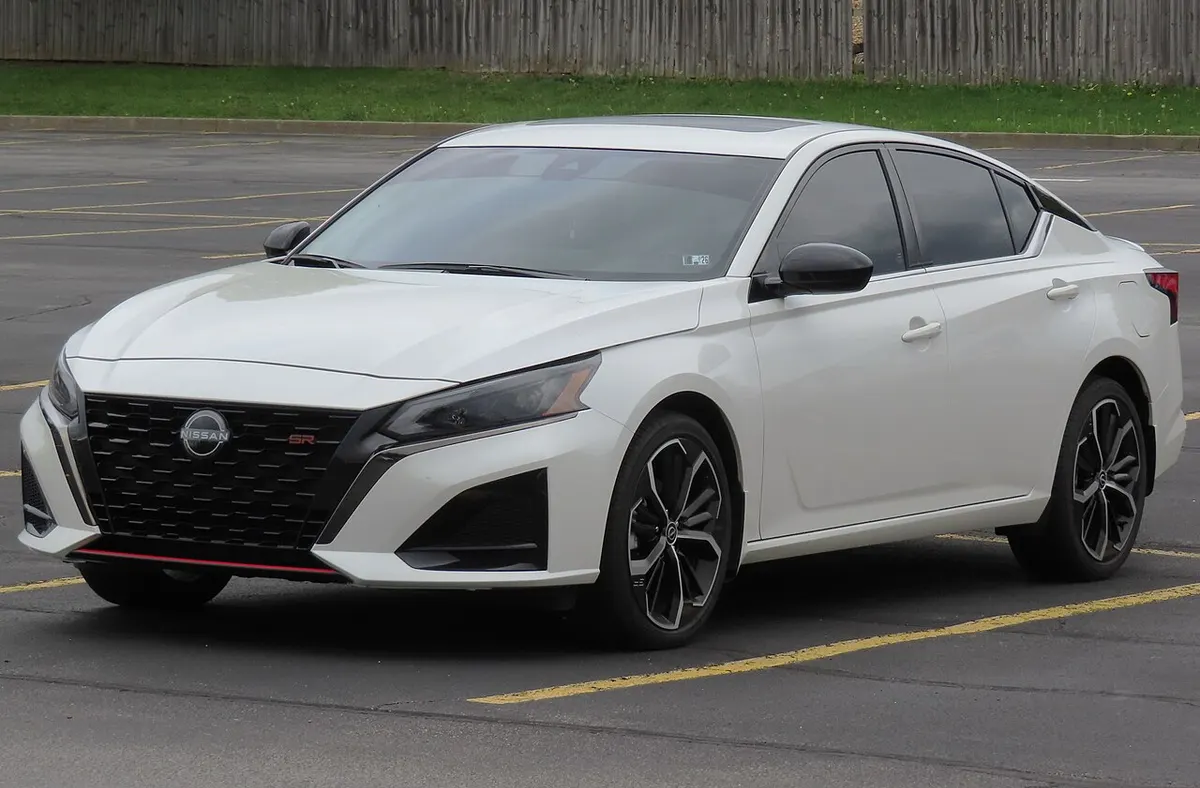 2024 Nissan Altimaabout $2,290 (about the same)
Photos from Wikimedia Commons contributors. Photo credits.
What a Kia K5 costs in your state
In six sample states, a 2024 Kia K5 runs from about $1,510 a year in Vermont through North Carolina, West Virginia, Oklahoma and Nevada to about $3,000 in New York:
- Vermontabout $1,510/yr · +$1,000 teen
- North Carolinaabout $1,730/yr · +$1,140 teen
- West Virginiaabout $1,940/yr · +$1,280 teen
- Oklahomaabout $2,090/yr · +$1,380 teen
- Nevadaabout $2,530/yr · +$1,670 teen
- New Yorkabout $3,000/yr · +$1,980 teen
All 50 states and DC · Updated .
Both start from your own situation if you've set one. For crash safety, see IIHS and NHTSA ratings.
This is an estimate to help you plan, not a quote. We don't sell insurance, and nothing you type is sent to us. Only an insurer can give you a real price.